Nigeria’s Dividend Tax Rules—Here’s What Investors Need to Know in 2026
If you’re thinking about buying Nigerian shares—especially as a foreign investor—there’s one number that can be surprisingly easy to overlook. It’s not the share price. It’s not even the dividend yield.
It’s the tax.
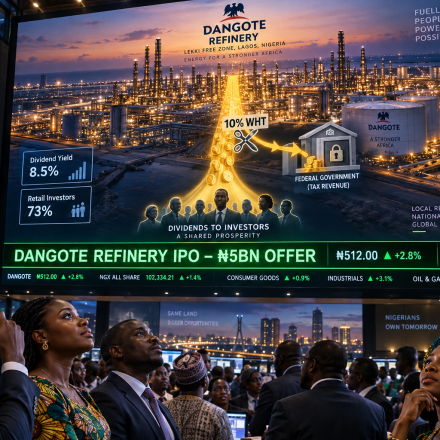
This matter came to the fore again. On August 26, 2026, there was this news story on Reuters.com with the headline: “Nigeria’s Dangote refinery nears record IPO, investors focus on oil supply costs”. The content of the story read that Dangote Refinery—a private company in Nigeria owned by the business mogul, Dangote—is seeking to raise a whooping sum of $5 billion (i.e., approximately =N=6.637 trillion) via Initial Public Offer (IPO). This is considered by analysts to be the largest offer so far in Africa.
And, understandably, an offering involving a business associated with Aliko Dangote is likely to attract considerable attention from institutional investors, wealthy individuals and foreign investors.
But buying the shares is only half the calculation. What happens when the dividends start arriving? Because the figure that ultimately matters isn’t necessarily the dividend a company declares. For an investor, what matters is what remains after tax.
What exactly is a dividend?
First, what is a dividend?
Click here for a reliable & affordable domain name and web hosting.
Often, a company makes money, distributes some of its profit to shareholders and calls the payment a dividend. But under the Nigeria Tax Act 2025, which came into force on January 1, 2026, the concept is broader than the cash payment that ordinarily comes to mind when investors hear the word dividend.
For a company that is a going concern—that is, a business expected to continue operating for the foreseeable future—a dividend includes a shareholder’s share of distributable profits. But interestingly, the dividend may necessarily not be received in cash. This distribution can also include bonus shares, debentures or other securities.
So if you’ve always thought of a dividend as money landing in your bank account after a company announces its annual results, that’s not the full story.
But what about a company being liquidated? The definition of a dividend goes further. Where a company is undergoing liquidation, dividend can include money—or the equivalent of money—earned by a shareholder during or before the liquidation, including distributions involving shares or other securities.
The Act also brings certain compensating payments into the definition such as a payment received by a lender of securities from a borrower or the borrower’s approved agent.
Though, these definitions seem a little technical, yet this distinction matters because tax law isn’t particularly interested in what investors casually call a payment. What matters is how the law characterises it. And those two things aren’t always identical.
Cash dividend versus scrip dividend—what’s the difference?
Broadly, dividends can be divided into two categories: cash dividend and script dividend. Cash dividends are exactly what they sound like. The shareholder receives such dividends in the form of money. But scrip dividends are distributions made in shares or other securities rather than cash.
Under the treatment described in the Nigeria Tax Act 2025, scrip dividends are not taxable, so no cash tax is paid on them. That distinction can make a meaningful difference to an investor comparing two apparently similar distributions. Same company profit. Same shareholder. Different method of distribution. One in the form of cash, and the other in the form of shares or other securities. And much more importantly: Different implications in term of tax.
It’s therefore funny how one word on a corporate-action notice can suddenly become rather important.
Why does the gross dividend matter?
Here’s another detail investors—and even businesses—can easily miss. Dividend income is recorded at its gross amount, not merely the amount that eventually reaches the recipient.
Suppose Company A is entitled to a ₦10 million dividend and 10% tax is deducted at source as withholding tax. Company A therefore receives ₦9 million in cash.
But ₦9 million isn’t the dividend figure to be recognised merely because that’s what arrived in Company’s bank account. The gross dividend is ₦10 million: the ₦9 million received plus the ₦1 million deducted as tax.
What law now governs dividend taxation in Nigeria?
Before 2026, investors had to deal with dividend-related provisions spread across several Nigerian tax laws, including the Companies Income Tax Act, Personal Income Tax Act, Petroleum Profits Tax Act etc.
That changed with the Nigeria Tax Act 2025, which came into force on January 1, 2026. The new Act consolidated and updated major elements of Nigeria’s tax legislation.
Section 4 of the Act specifically treats dividend as income and therefore brings it within the country’s income-tax framework. For somebody buying Nigerian shares in 2026, this is important. Old articles, old investment guides and that tax explanation somebody bookmarked three years ago may no longer tell the whole story.
Who actually pays tax on dividends?
Almost anyone earning taxable dividends in Nigeria needs to understand the rules, but investors can conveniently be grouped into three broad categories:
1. Nigerian individual shareholders
2. Nigerian corporate shareholders
3. Non-resident or foreign shareholders
The basic idea is similar. The tax consequences aren’t necessarily identical. Therefore, let’s take them one at a time.
How are Nigerian individual shareholders treated? A Nigerian individual shareholder is a person who owns shares in a Nigerian company and becomes entitled to part of the company’s distributable profit when a dividend is declared. But there’s a timing issue worth noticing.
Under the Nigerian tax treatment described in the Act, dividend income is regarded as earned when the dividend becomes due, not simply when the shareholder eventually receives the money.
Imagine a dividend becomes due in December but doesn’t arrive in your bank account until January. The bank alert may say January. But for tax purposes, however, December may be the important date.
What if the shareholder is another Nigerian company? A Nigerian corporate shareholder is simply a Nigerian company holding shares in another company and therefore entitled to dividends when those dividends are declared. For example, Company X invests in Company Y. Therefore, Company X is a shareholder in Company Y.
When dealing with this type of issue, the important expression here is franked investment income. Where withholding tax has already been deducted from the dividend at source, that deduction is treated as the final tax on that dividend income. The dividend received by the corporate shareholder is consequently excluded from the profits or income otherwise taxable under the relevant provision of the Nigeria Tax Act 2025.
In practical terms, the system recognises that tax has already been suffered at source. And therefore, there’s no need to pretend it didn’t happen.
And foreign or non-resident investors?
Now we get to the category that could become particularly more relevant if the proposed Dangote Refinery IPO attracts international investors.
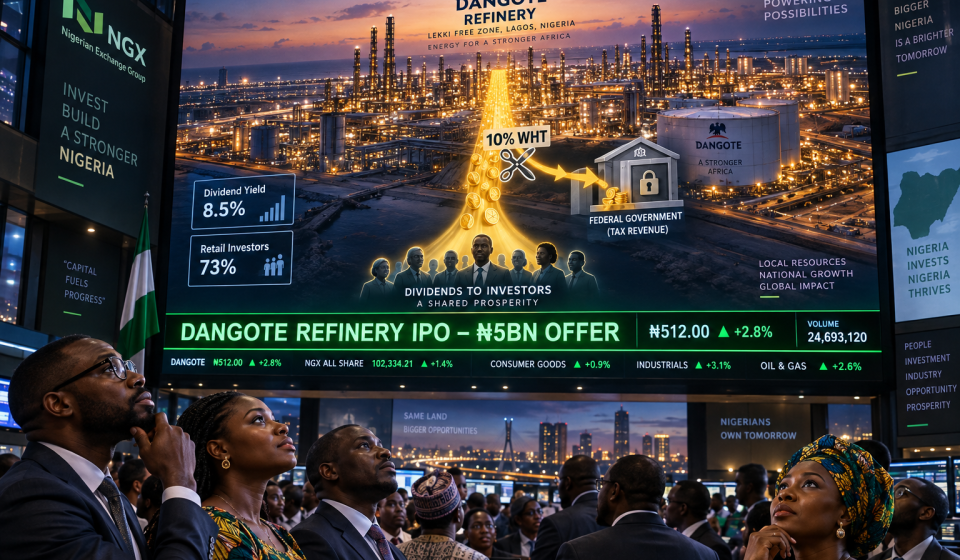
A non-resident or foreign shareholder holding shares in a Nigerian company may receive dividends from those shares. Those dividends are subject to withholding tax deduction in Nigeria at 10%, with that deduction treated as the final Nigerian tax on the dividend income. That makes the tax rate an important part of the investment calculation.
Suppose you’re comparing Nigerian equities with investments elsewhere. A headline dividend yield may look attractive, but the useful comparison is generally the return you actually retain especially after the deduction of tax.
Though gross yield gets the attention. But after-tax yield pays the bills.
What about mutual funds and unit trusts?
Owning units in an investment fund can look quite different from buying shares in an individual company, but the law also deals with this situation. Unit holders in mutual funds and other investment funds are treated as shareholders for this purpose. Their units are treated as shares, while income available for distribution to them under the trust arrangement is treated as dividend income.
Therefore, an investor shouldn’t automatically assume that using a collective investment vehicle takes dividend taxation out of the picture. It’s just a different wrapper with similar question.
Are dividends from Nigerian companies considered Nigerian income?
Yes. Dividends distributed by Nigerian companies are treated as Nigerian-sourced income.
That’s important because the location of the investor doesn’t, by itself, transform the source of the income. If the dividend arises from the Nigerian company, the Nigerian tax rules enter the calculation. For instance, you may be resident in Canada but you derived dividend from a company registered and resident in Nigeria. Such dividend is deemed as Nigerian income.
This presupposes that a foreign investor assessing an IPO such as Dangote Refinery’s proposed offering should examine taxation alongside valuation, earnings, crude-oil supply, exchange-rate exposure and the company’s dividend prospects.
Tax isn’t an appendix to the investment decision. It’s part of the return. It’s part of the whole picture.
What happens if a Nigerian resident receives foreign dividends?
Now let’s turn this around. Suppose you live in Nigeria but own shares in a company outside the country. What happens when that company pays you a dividend?
Section 163 of the Nigeria Tax Act 2025 provides that foreign dividend brought into Nigeria through approved channels is excluded from tax. The Act, as discussed here, does not expressly define what constitutes an “approved channel.” A reasonable interpretation may point toward appropriately authorised financial institutions regulated by the government especially through the Central Bank of Nigeria or Ministry of Finance.
Still, this is one of those places where assumptions can become expensive. If a substantial amount is involved, the precise route through which foreign dividend income enters Nigeria deserves attention.
What if a company pays dividends from retained earnings?
Here’s where things become more interesting. Companies don’t always pay dividends from the profit earned in the current year. Sometimes current-year profit is too small. Sometimes there is no current-year profit at all. Yet the company has accumulated profits from previous years—its retained earnings—and decides to distribute part of those reserves to shareholders.
Nigeria’s tax rules contain provisions designed to prevent this mechanism from being used for tax avoidance.
Where a company has no taxable profit, or has profit on which no tax is payable, but nevertheless declares a dividend, the law may treat the amount of dividend declared as though it were the company’s total profit for that year and apply the relevant company income-tax rate.
Let’s take a simple example. A company earns no taxable profit during the year but declares a ₦10 million dividend from retained earnings. Under the rule, that ₦10 million can be deemed to be the company’s total profit for the relevant year of assessment and taxed accordingly.
This may sound severe. There are, however, important exceptions which are considered in the next section.
When does the retained-earnings rule not apply?
If the retained earnings came from profits that had already suffered income tax in an earlier period, the rule in the above section does not apply merely because those profits are being distributed later.
Likewise, dividends declared from profits or gains exempt from income tax are outside the rule. In the same vein, franked investment income—dividend income that has already suffered the appropriate deduction at source—is also exempt. So also, distributions by real estate investment companies to their shareholders receive their own exemption from this treatment.
The underlying logic isn’t difficult to see: the provision is aimed at untaxed profits, not at finding creative ways to tax the same already-taxed profit again.
What was dividend taxation like before 2026?
For investors who have been in the Nigerian market for some time, some of these ideas will sound familiar. Before the Nigeria Tax Act 2025 took effect, dividend taxation was governed through laws including the Personal Income Tax Act.
Under that earlier framework, dividends were generally taxable and dividends from Nigerian companies were treated as Nigerian-source income. The older regime also contained rules covering foreign dividends, timing of dividend income, exemptions for particular investments and withholding tax.
For Nigerian dividends, companies generally deducted 10% withholding tax before paying the balance to shareholders. So if ₦100,000 was declared, ₦10,000 went to the tax authority and the shareholder received ₦90,000. Such withholding tax was generally treated as final tax on the dividend income.
The take-away here is, the new regime in term of dividend taxation is not substantially different from the old one. The rate is still at 10%.
Why should an investor care about all this?
Because investors don’t consume percentages. They consume returns.
Imagine two investments both advertise a 10% dividend yield. If their tax treatments differ, the investor may not actually receive the same return from both. And for institutional and foreign investors dealing with millions—or billions—the difference between gross income and after-tax income can become substantial very quickly.
Which brings us back to Dangote Refinery.
Reuters reported that the company was expected to seek about $5 billion in an IPO, potentially Africa’s largest listing yet. For prospective investors, much of the immediate attention will understandably fall on crude-oil supply, refining margins, capacity expansion, valuation and earnings. Which are all valid questions.
But should the company eventually become a major dividend payer, another question will matter too: How much of that dividend does the investor actually keep? This is not quite as exciting as discussing Africa’s biggest IPO. But may be quite telling on your investment return when the time comes.
The dividend-tax points investors should remember
If you’re investing in Nigeria in 2026, these are the practical points worth keeping close:
- Dividends are income. Under the Nigeria Tax Act 2025, dividend falls within the country’s income-tax framework.
- A dividend isn’t necessarily cash. The statutory concept extends beyond ordinary cash distributions and can include bonus shares, debentures, securities and certain payments associated with liquidation or securities lending.
- Gross and net dividend aren’t the same thing. Where tax has been deducted at source, the dividend is still recognised at its gross amount.
- Timing matters. Dividend income may be treated as earned when it becomes due rather than when the money eventually arrives.
- Corporate investors have special treatment. Dividend that has suffered withholding tax at source can constitute franked investment income, with the withholding tax treated as final tax.
- Foreign shareholders aren’t outside the system. Dividend from Nigerian companies received by non-resident investors is subject to Nigerian withholding-tax rules, with the deduction treated as final Nigerian tax on that dividend income.
- Foreign dividends received by Nigerian residents require a different analysis. Section 163 provides an exclusion where qualifying foreign dividend is brought into Nigeria through approved channels.
- Retained earnings deserve attention. A company with no taxable profit that nevertheless declares dividends may face tax based on the amount distributed, although important exceptions exist for previously taxed retained earnings, exempt profits, franked investment income and qualifying real-estate investment-company distributions.
And perhaps the easiest rule to remember?
Don’t judge an investment by its gross dividend alone. A 12% dividend isn’t really a 12% return to you if tax changes what eventually reaches your pocket.
What should you check before buying a Nigerian dividend stock?
Always start with the obvious numbers: earnings, dividend history, payout ratio, cash flow and expected yield. Then go one step further by asking what tax applies to you.
Are you an individual Nigerian investor? A Nigerian company? A mutual-fund investor? Or a foreign shareholder?
How will the dividend be distributed? Has tax already been deducted at source? Does an exemption apply? If you’re bringing foreign dividend income into Nigeria, does the method of remittance satisfy the applicable requirements?
Those questions aren’t nearly as glamorous as predicting where a share price will go. But investment returns have an irritating habit of becoming much more interesting after taxes are deducted.
And with a potential $5 billion Dangote Refinery IPO bringing fresh attention to Nigerian equities, understanding the difference between the dividend a company announces and the dividend an investor ultimately keeps may be more useful than ever. Because when the dividend alert finally arrives, there’s really only one figure that matters.
The amount that’s yours.


HELLO